How Startup Equity Actually Works (Explained Simply)
Dorthy Leon
September 23, 2026
Startup equity can sound unnecessarily complicated. Founders talk about shares, ownership percentages, option pools, dilution, vesting, valuations, and funding rounds as though everyone already understands what those terms mean.
Underneath all that terminology, the basic idea is much simpler: equity represents ownership in a company.
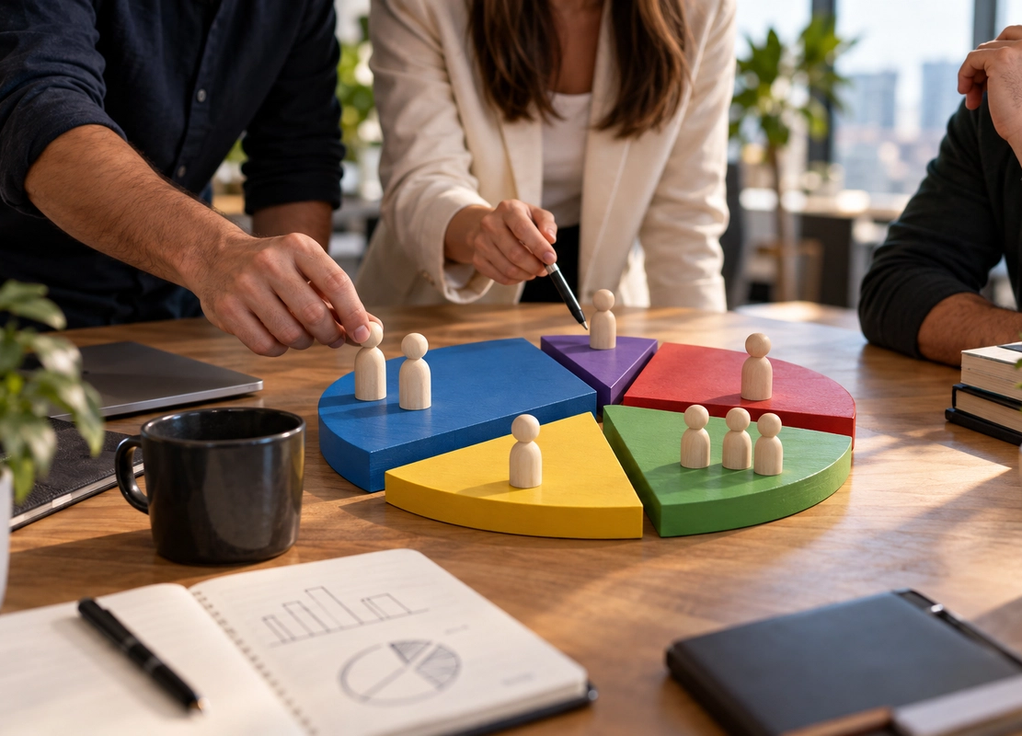
If you own 20% of a startup, you own 20% of that company at that point in time. But startup ownership rarely stays fixed. As investors put money into the business, employees receive stock options, and additional shares are created, everyone’s percentage can change.
Understanding how that happens makes startup equity much easier to follow.
Equity starts with the founders
Imagine two founders create a company together. At the beginning, they agree to split ownership equally.
Founder A owns 50%, and Founder B owns 50%.
If the company has 1,000 shares, each founder could own 500. The number of shares is largely a way of dividing ownership into units. What usually matters most is the percentage of the total company those shares represent.
Founders do not always divide equity equally. One person may have developed the idea earlier, invested more money, worked full time while another worked part time, or brought particularly important technology or expertise.
Whatever split they choose, it is worth treating the decision seriously. Founder equity can become extremely valuable if the company succeeds.
There is also an important difference between owning shares and receiving cash. A founder who owns 50% of a startup valued at €10 million does not necessarily have €5 million sitting in a bank account. The value exists primarily on paper until there is a way to sell those shares or otherwise realize their value.
Investors exchange money for ownership
Suppose the startup needs capital to hire employees and develop its product.
An investor agrees to invest €1 million. In return, the investor receives shares in the company.
The amount of ownership depends on the company’s valuation and the specific terms of the investment. In a simplified example, imagine the founders and investor agree that the company is worth €4 million before the investment. This is called the pre-money valuation.
After the investor adds €1 million, the post-money valuation becomes €5 million.
The investor’s €1 million therefore represents 20% of the post-money company in this simplified scenario.
The original shareholders collectively own the remaining 80%.
The founders have not necessarily lost shares. Instead, new shares have typically been issued to the investor, increasing the total number of shares outstanding. That reduces the percentage represented by each existing share.
This process is called dilution.
Dilution does not automatically mean losing value
Dilution often sounds frightening because someone’s ownership percentage becomes smaller.
Imagine a founder owns 50% of a startup before an investment round. After new shares are issued, the founder’s ownership falls to 40%.
They have been diluted.
But percentage ownership is only part of the equation.
Suppose the company was worth €2 million when the founder owned 50%. Their stake would theoretically represent €1 million. Years later, perhaps they own only 20% because several investment rounds have occurred, but the company is now worth €100 million.
That 20% would theoretically represent €20 million.
In this simplified example, the founder owns a smaller portion of something dramatically more valuable.
Of course, startup valuations can change, shares may have different rights, taxes can apply, and a company’s headline valuation does not guarantee that every shareholder could sell at that price. But the example explains why dilution itself is not necessarily negative.
The important question is what the company receives in exchange for that dilution.
Employees can receive equity too
Startups often use equity to attract employees, particularly when they cannot match the salaries offered by larger companies.
Employees may receive stock options rather than shares immediately. A stock option generally gives someone the right to purchase shares later at a predetermined exercise price, subject to specific conditions.
Companies frequently create an option pool—a portion of the company’s equity reserved for current and future employees.
An employee might receive options representing 0.5% of the company when the grant is made. If the startup becomes significantly more valuable, those options could eventually become valuable too.
But receiving “0.5% equity” does not mean receiving 0.5% of the company’s current valuation in cash.
The options may need to vest, the employee may need to exercise them, the ownership percentage may later be diluted, and there may not yet be any market where the shares can easily be sold.
Startup equity is therefore potential financial value rather than guaranteed compensation.
Vesting determines when equity is earned
Founders and employees frequently receive equity subject to vesting.
Vesting means ownership rights are earned over time rather than becoming fully available immediately.
A common structure is four-year vesting with a one-year cliff. Under this arrangement, someone generally earns no vested equity until completing the first year. At that point, a portion becomes vested, and the remainder continues vesting gradually over the following three years.
Why structure equity this way?
Imagine giving a co-founder 40% of the company on day one and having that person leave after two months. Without appropriate agreements, the remaining founder could potentially spend years building a company while the former co-founder retains a very large ownership stake.
Vesting helps align equity with continued contribution.
The exact structure varies by company and jurisdiction, so the legal documents matter considerably.
Funding rounds keep changing the ownership table
As a startup grows, it may raise several rounds of funding.
After the founders create the company, angel investors might participate. Later there could be seed funding, followed by Series A, Series B, and additional rounds.
Each round can introduce new shareholders and create additional shares.
The company tracks all of this through a capitalization table, commonly called a cap table. The cap table records who owns shares or other equity interests and how those holdings relate to the company’s overall ownership structure.
A startup might eventually have founders, employees, angel investors, venture capital funds, and other shareholders on its cap table.
This is why a founder who began with 100% ownership might eventually own 30%, 15%, or even less while still remaining a major shareholder.
Equity becomes real money only under certain circumstances
The final piece of the puzzle is liquidity.
A startup can be valued at hundreds of millions of euros while its founders and employees still hold shares that are difficult to sell.
Equity typically becomes easier to turn into cash when something creates liquidity. The company might be acquired, go public, allow shareholders to participate in a secondary sale, or facilitate another transaction where shares can be sold.
Until then, much of the wealth associated with startup equity may exist only on paper.
And even when an exit happens, the final payout can depend on the company’s capital structure, investor rights, taxes, exercise costs, and other terms.
That is why startup equity should never be understood simply as “my percentage multiplied by the company’s valuation.”
At its core, though, the concept remains straightforward. Equity is ownership. Investment can dilute that ownership. Vesting determines when certain equity is earned. And the eventual value depends on what happens to the company.
Once those four ideas are clear, the complicated language surrounding startup equity becomes much easier to understand.